The January Problem: A Structural Case for Staggered Reporting Cohorts in Making Tax Digital
A discussion on the design of MTD for Income Tax Self-Assessment
Acknowledgments
This discussion paper has been extensively reviewed using an AI assistant (Lumo, developed by Proton). Lumo assisted with fact-checking against primary sources including HMRC press releases, GOV.UK guidance, ICAEW Insights, ICAS responses, and ATT technical notes; verification of arithmetic calculations across all cohort schedules; identification of internal contradictions between sections; and suggestions for structural refinements including the reordering of objections and the development of the congestion-relief claim. All arguments, conclusions and any remaining errors are the sole responsibility of the author.
The author welcomes formal feedback from professional bodies, HMRC stakeholders or academic reviewers. Such engagement may inform future revisions.
Introduction
Making Tax Digital for Income Tax Self-Assessment (MTD for ITSA) went live on 6 April 2026 for sole traders and landlords with qualifying income above £50,000, bringing more than 864,000 taxpayers into scope with the first tranche (HMRC, 2026a). Further tranches with thresholds of £30,000 from April 2027 and £20,000 from April 2028 are estimated to increase the size of the mandated population considerably, adding approximately 1,077,000 taxpayers in April 2027 (HM Government, 2026a). On that trajectory — with a similar increase expected when the £20,000 threshold applies from April 2028 (HM Government, 2026b) — the total mandated population could reasonably exceed 3,000,000.
The reform replaces the annual Self-Assessment return with quarterly digital updates and an end-of-year final declaration. Yet despite the most significant redesign of income tax reporting in a generation, one feature has been carried over untouched: the near-total synchronisation of reporting periods and deadlines — everyone reports on the same cycle (6 April to 5 April)1, and crucially, everyone finalises on 31 January the following year.
This discussion argues from a system design perspective that this synchronisation is a design flaw, with real costs — foremost among them an information gap that leaves taxpayers operating on estimates for up to nine months after their year-end. Closing that gap should be regarded as the primary outcome any redesign of the reporting calendar delivers.
The proposed remedy has not featured in HMRC’s published thinking: staggered reporting cohorts, in which newly mandated taxpayers would report on a different annual cycle, leaving existing users’ reporting on the 6 April to 5 April cycle, and in which each cohort’s final declaration falls within 90 days of its year end, before its next quarterly update.
A further issue deserves candid acknowledgement. After all announced tranches have taken effect, the mandated population is projected to remain roughly a quarter of the Self-Assessment population. The challenge this arithmetic poses to the case for the reform is set out later in this discussion, in “A question of scope: what is the disruption for?”.
Discussion is confined to system architecture — deadline structure, how deadlines concentrate demand on agents and HMRC infrastructure, throughput, bottlenecks and scalability — leaving open how the proposal would operate within real practice, which is exactly the perspective practitioners and their professional bodies are best placed to supply.
The more fundamental question of whether the reform should extend as far as it does, which the scope question raises but does not resolve, also remains open.
The 9-month information gap
The commonly cited objection to the January final declaration deadline is overload, but the more serious problem concerns asymmetry of information.
The owner of a business closing its books on 5 April doesn’t finalise its position immediately but waits until its final declaration is due the following 31 January. For up to nine months, the business operates without a confirmed net profit or liability for the year just ended. Cash-flow planning, tax provisioning and investment decisions all proceed on estimates.
The architecture of MTD was supposed to improve this. Quarterly updates were intended to give taxpayers near-real-time visibility of their tax position. But two features of the initial design undermine that promise.
First, quarterly updates are explicitly provisional. HMRC’s guidance is direct: “You do not need to make any accounting or tax adjustments before sending a quarterly update” (HMRC, 2026b). The updates are summaries, not tax returns, and capital allowances, loss relief and other end-of-period corrections are deferred to the final declaration. The estimates taxpayers receive therefore exclude precisely the adjustments that determine actual profit and tax liability. The professional bodies concur: ICAS, in its response to HMRC’s consultation on timely payment of income tax (published 23 June 2026), warned that MTD updates “are not currently tax-adjusted and will, in all but the simplest of cases, be unsuitable for estimating annual taxable profits”, particularly where year-end tax planning and capital expenditure affect the liability (ICAS, 2026b).
Second, the figures downstream of quarterly reporting depend on the previous year’s finalised results. Payments on account for 2026/27 are calculated from the 2025/26 liability, which is itself not confirmed until 31 January 2027 — the same date on which the balancing payment falls due. The in-year tax estimates built on those updates therefore inherit the prior year’s unresolved adjustments and cannot firm up until those are complete. The system thus embeds a recurring, compounding lag that concentrates its consequences in a single month.
The congestion problem
Even in the best case, synchronisation creates predictable congestion. As each tranche of the thresholds brings in hundreds of thousands of new users — the £50,000 tranche alone brought more than 864,000 taxpayers into scope (HMRC, 2026a), with approximately 1,077,000 more expected from April 2027 (HM Government, 2026a) — onboarding and agent authorisations cluster around the same April dates. Early evidence bears this out: HMRC reported over 570,000 registrations and around 436,000 first quarterly submissions as of 12 August 2026 (HMRC, 2026c) — leaving a gap between the populations expected in scope and those actively reporting. Despite having allowed the sign-up process for MTD a year early (HMRC, 2025), agents faced registration and authorisation failures as the first 2026/27 quarterly period end approached (ATT, 2026), and by August 2026 roughly a third of the in-scope population remained unregistered, prompting HMRC to adopt staged automatic enrolment (HMRC, 2026c). That staging may be read as a silent admission that simultaneous onboarding strains the system.
Professional bodies have voiced related concerns. Referring to taxpayers with qualifying income of more than £20,000 from self-employment and property, due to register in April 2028, the ICAEW has questioned the pace of extension given that the first mandatory year-end returns are not due until 31 January 2028, leaving “almost no time to assess how that has gone before the requirements are extended to more taxpayers” (Miskin, quoted in ICAEW, 2025). ICAS reached a similar conclusion earlier still: writing to the minister responsible in June 2023, ICAS argued that quarterly reporting requirements would impose a disproportionate cost burden on smaller businesses and urged that quarterly mandates apply only above the VAT registration threshold — a warning premised on its estimate that only around 5% of UK accountancy firms were then truly digital (ICAS, 2023a; 2023b).
The structural irony deserves emphasis: basis period reform (Finance Act 2022) deliberately abolished the old ‘current year basis’ and aligned all unincorporated businesses to the tax year. In its consultation, HMRC stated that these reforms were intended to ‘simplify the taxation of trading profits and the implementation of Making Tax Digital for Income Tax’ (Tax Adviser magazine, 2023). Yet as Tax Adviser magazine observed, for businesses with year-ends not aligned to 5 April, quarterly reports of receipts and expenses will not match taxable profit at all, since profit must be time-apportioned across accounting periods. And it remains unclear how software will bridge that gap (ATT, 2024). Alignment has solved one problem and created another.
Why “file early” is not an answer
At this point a natural objection arises — none of this regulation prevents early finalisation. Returns can be submitted at any point after the tax year ends (31 January is a deadline, not a start date). If a business with closed books can finalise in April, doesn’t the January peak then reflect taxpayers’ own choices?
This objection is correct in its facts, but its conclusion deserves further analysis.
Voluntary early filing has existed throughout the Self-Assessment era, and the scale of the January concentration that follows from taxpayers declining to use it is official, not inferred. HMRC’s own figures show that on 5 January 2026 — with less than a month to go — 5.65 million taxpayers had still to file, nearly half of the more than 12 million expected to submit a return for 2024/25 (HMRC, 2026d). It is true that a narrow majority, 6.36 million, had already completed their return by that date, and that thousands filed over the New Year holiday itself. But that concession makes the point more sharply, not less: even after three decades of publicity urging the opposite, close to half the entire Self-Assessment population reliably arrives in the final four weeks. The reason is not laziness but rationality. A taxpayer who finalises early receives no benefit whatsoever: the balancing payment is still due on 31 January, payments on account still fall on 31 January and 31 July, and any repayment accrues no additional interest by arriving sooner. Early filing costs effort now while deferring settlement by up to nine months — for HMRC’s benefit, not the taxpayers. Money left in the taxpayer’s hands until the deadline is money working for the taxpayer, not the Treasury.
The January congestion is therefore best understood not as a failure of individual discipline but as a coordination failure with individually rational causes. Millions of taxpayers, each responding sensibly to the incentives they face, collectively produce an outcome nobody wants; overloaded agents, jammed HMRC helplines, and a compressed professional season that degrades the quality of year-end work.
Nor is the helpline strain hypothetical. As 31 January 2026 fell on a Saturday, HMRC’s Agent Dedicated Line was closed on the deadline day itself — shutting at 6pm on Friday 30 January and reopening Monday 2 February — HMRC providing an enhanced webchat service for taxpayers and agents, with more advisers than usual to provide support, and phone helplines, restricted to a limited Saturday window of a few hours covering only common queries (ICAS, 2026a; ICAEW, 2026). When the system’s answer to its own busiest day is to close its main agent support channel and triage everything else, it is managing the congestion rather than addressing it. “File early” campaigns and awareness messaging ask taxpayers to act against their own financial interest with no compensating reward, and the persistence of a five-million-plus January backlog demonstrates that they have never succeeded at scale. There is no reason to believe they will under MTD.
Before drawing conclusions from that backlog, one difference in scale should be stated plainly. The 5.65 million unresolved filings belong to the entire Self-Assessment population — more than 12 million taxpayers — whereas MTD for ITSA presently reaches only the first mandated tranche of roughly 864,000, estimated to grow by around 1,077,000 in April 2027 with a similar increase expected in April 2028 (HM Government, 2025; HM Government, 2026a, 2026b). The figure is therefore not a like-for-like count of current MTD congestion and should not be presented as one. Its proper use is as a behavioural benchmark: the share of taxpayers — close to half — who defer filing to the final month when the final declaration and payment deadlines coincide on 31 January. Nothing in the design of MTD removes the incentive producing that behaviour. The smaller, higher-income and better-advised early cohorts may file earlier in aggregate, but there is no basis for expecting the final-month concentration to disappear as the MTD population grows in size. Announced policy restricts the ultimate size of the mandated MTD population and skews its composition relative to Self-Assessment. Once all three tranches have taken effect, the mandated MTD population is projected to be in the order of 3 million — roughly a quarter of the more than 12 million expected to file — a proportion examined further in the next section.
One consequence follows directly, also worth stating plainly: because payment deadline dates are involuntary anchors, even perfect compliance with an ideal of April filing would leave the January peak intact. Millions of balancing payments would still land simultaneously in January, followed by a second spike on 31 July. Spreading reporting through voluntary behaviour does nothing about the settlement schedule, because payment deadlines are compulsory regardless of when the return was submitted.
A question of scope: what is the disruption for?
A design discussion owes the reader an answer to a more fundamental challenge, and transparency requires stating it in its strongest form.
Once the thresholds of £50,000, £30,000 and £20,000 have all taken effect, the mandated population — more than 864,000 in scope today, rising by approximately 1,077,000 in April 2027 with a similar increase expected in April 2028 — will total in the order of 3 million taxpayers (HM Government, 2025; 2026a; 2026b). Against the more than 12 million expected to file Self-Assessment returns (HMRC, 2026d), that is roughly a quarter. The remaining three-quarters continue exactly as before: an annual return, finalised by 31 January, on the model this reform was introduced to replace.
The challenge follows directly from the government’s own chosen boundary. If digital record-keeping, quarterly updates and a final declaration justify the compliance costs imposed on the mandated minority, why do those benefits stop at a quarter of the population? And if extending them further is judged not worthwhile — as the £20,000 floor implies — then what, precisely, was the disruption for? At its strongest, the argument for abandoning the reform altogether rests on this arithmetic, and it is not an argument this paper attempts to rebut.
This challenge should not be ignored. The scope question and the design question are not independent, for three reasons.
First, unless and until the reform is halted or its thresholds revisited, the next tranches arrive on the current timetable. Whatever one’s conclusion on the ultimate case for MTD, the calendar within it is being operated now, by a mandated population that has already borne the onboarding and registration difficulties described above (ATT, 2026; HMRC, 2026c). The design of that calendar is a live question under every scenario except immediate repeal.
Second, the growth of the mandated population multiplies every MTD-specific congestion effect analysed in this paper: the January peak is a fixed property of the existing implementation, and the tranches determine how many taxpayers are subject to it. Limiting scope to a quarter of Self-Assessment, meanwhile, does nothing to reduce total January congestion as agents and HMRC experience it — it merely splits the combined taxpayer population in two without separating their declaration and payment deadlines.
Third, and most importantly, the information gap described in the opening of this discussion is borne by exactly that mandated quarter. If the costs of the disruption are to be carried by a minority, the minimum that minority is owed is a design that delivers the benefit the reform was named for: current, usable information about its tax position. Closing that gap — not the redistribution of administrative workload, which is a secondary effect — is the primary objective of the design set out in the remainder of this discussion.
Staggered cohorts — a candidate design
If the costs of synchronisation are real and voluntary behaviour cannot remedy them, the remedy must change the structure itself, distributing reporting deadlines and their associated payment deadlines across the calendar, and decoupling these two different kinds of deadlines altogether.
A design constraint deserves emphasis at the outset, because it defines what the proposal does and does not change. Tax liability itself would continue to be computed on the statutory tax year: rates, allowances, national insurance and benefit entitlements would remain untouched. The staggered cohort design would govern only when the final declaration is submitted, when quarterly updates fall due and when the associated payments crystallise. In other words, the cohort change is a stagger of deadlines and a separation of reporting deadlines from their associated payment deadlines, not of the underlying computation. This deliberately confines the proposal to what it needs to achieve and avoids reopening historic reconciliation machinery that basis period reform spent years dismantling — an issue explored further in the objections below.
The MTD Calendar
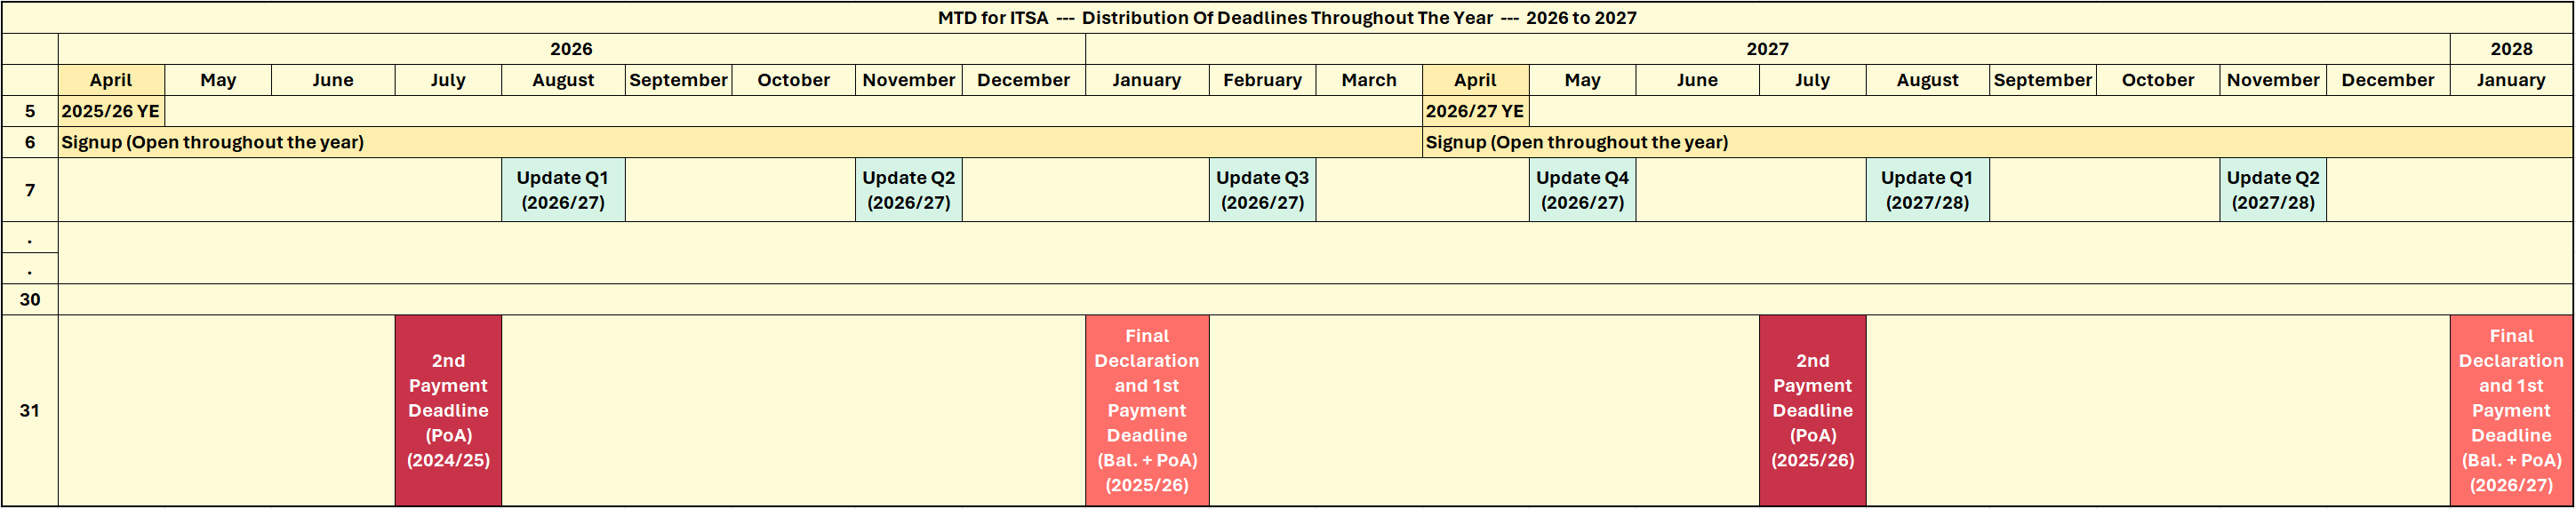
Figure 1 presents an analysis of the deadlines for taxpayers already using MTD for ITSA during the relevant tax year, beginning on 6 April 2026. Their first quarterly update fell on 7 August 2026 and within the twelve months from August 2026 through July 2027 only seven deadlines fall: the four quarterly updates for 2026/27, the final declaration (plus any balancing payment owed) for 2025/26, the first payment on account towards the 2026/27 tax bill (all due by 31 January 2027), and the second payment on account towards the 2026/27 tax bill (due by 31 July 2027). The corresponding declaration and payment obligations for the 2026/27 tax year fall later: the final declaration, balancing payment and first payment on account on 31 January 2028, and the second payment on account on 31 July 2028.
Click on the image to view a larger format.
The calendar in figure 1 exposes MTD's most significant weakness — the retained January reporting deadline conflated with one of only two annual payment deadlines. The fixed date on which this important reporting deadline falls accepts that 'rationally late' reporters are working with incomplete financial records on a perpetual annual cycle.
A staggered cohort design addresses the issues associated with synchronised universal deadlines and presents an opportunity to align every taxpayer's final declaration with their cohort's quarterly update schedule, in a way that closes the information gap. The two critical implementation requirements are separating the declaration and payment deadlines, and scheduling the final declaration deadlines to fall before each cohort's first quarterly update reporting deadline.
The following tables, calendars and discussion present the analysis of a phased transition between MTD's initial implementation and a staggered cohort design ending in a normalised annual reporting and payments schedule. The analysis follows the 'taxpayer's journey', through two consecutive tax years, 2027/28 and 2028/29, corresponding with the taxpayers coming into scope in tranches during these two periods.
Considering a hypothetical case where the government has decided to implement staggered cohorts, beginning with the April 2027 tranche of sole traders and landlords with qualifying income exceeding £30,000 per year, and continuing through April 2028, onboarding those with qualifying income exceeding £20,000 per year.
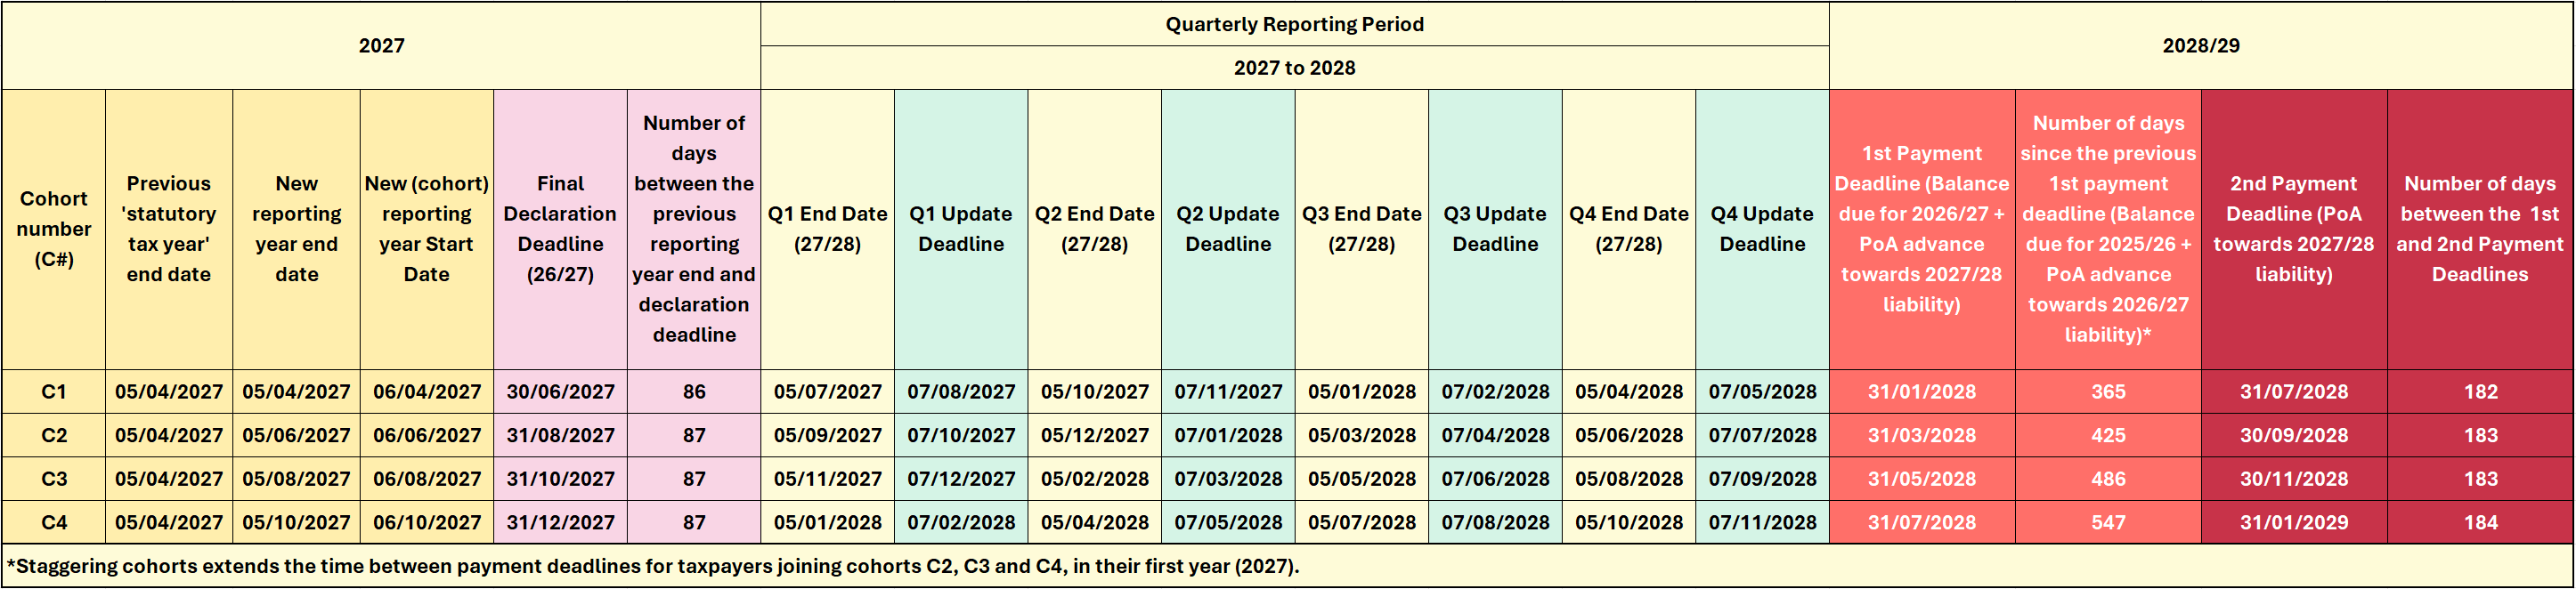
The transitional schedule of events and deadlines in the first year, beginning on 6 April 2027 is presented in figure 2. Figure 2.1 presents the staggered cohort calendar covering the tax year 2027/28.
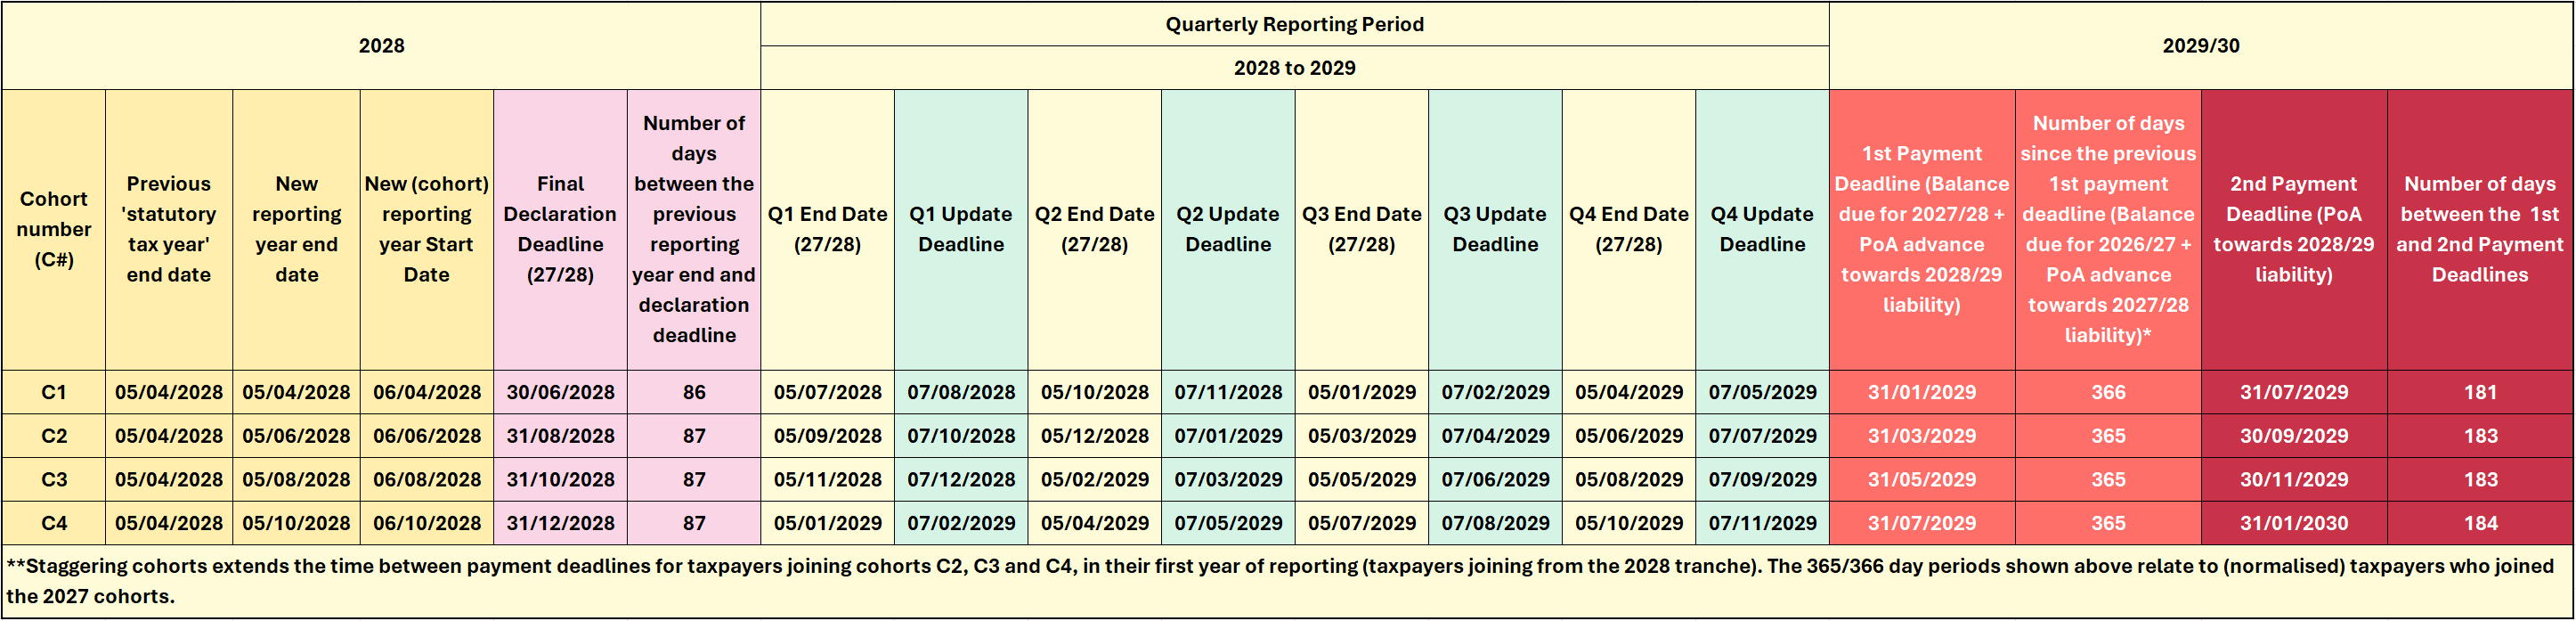
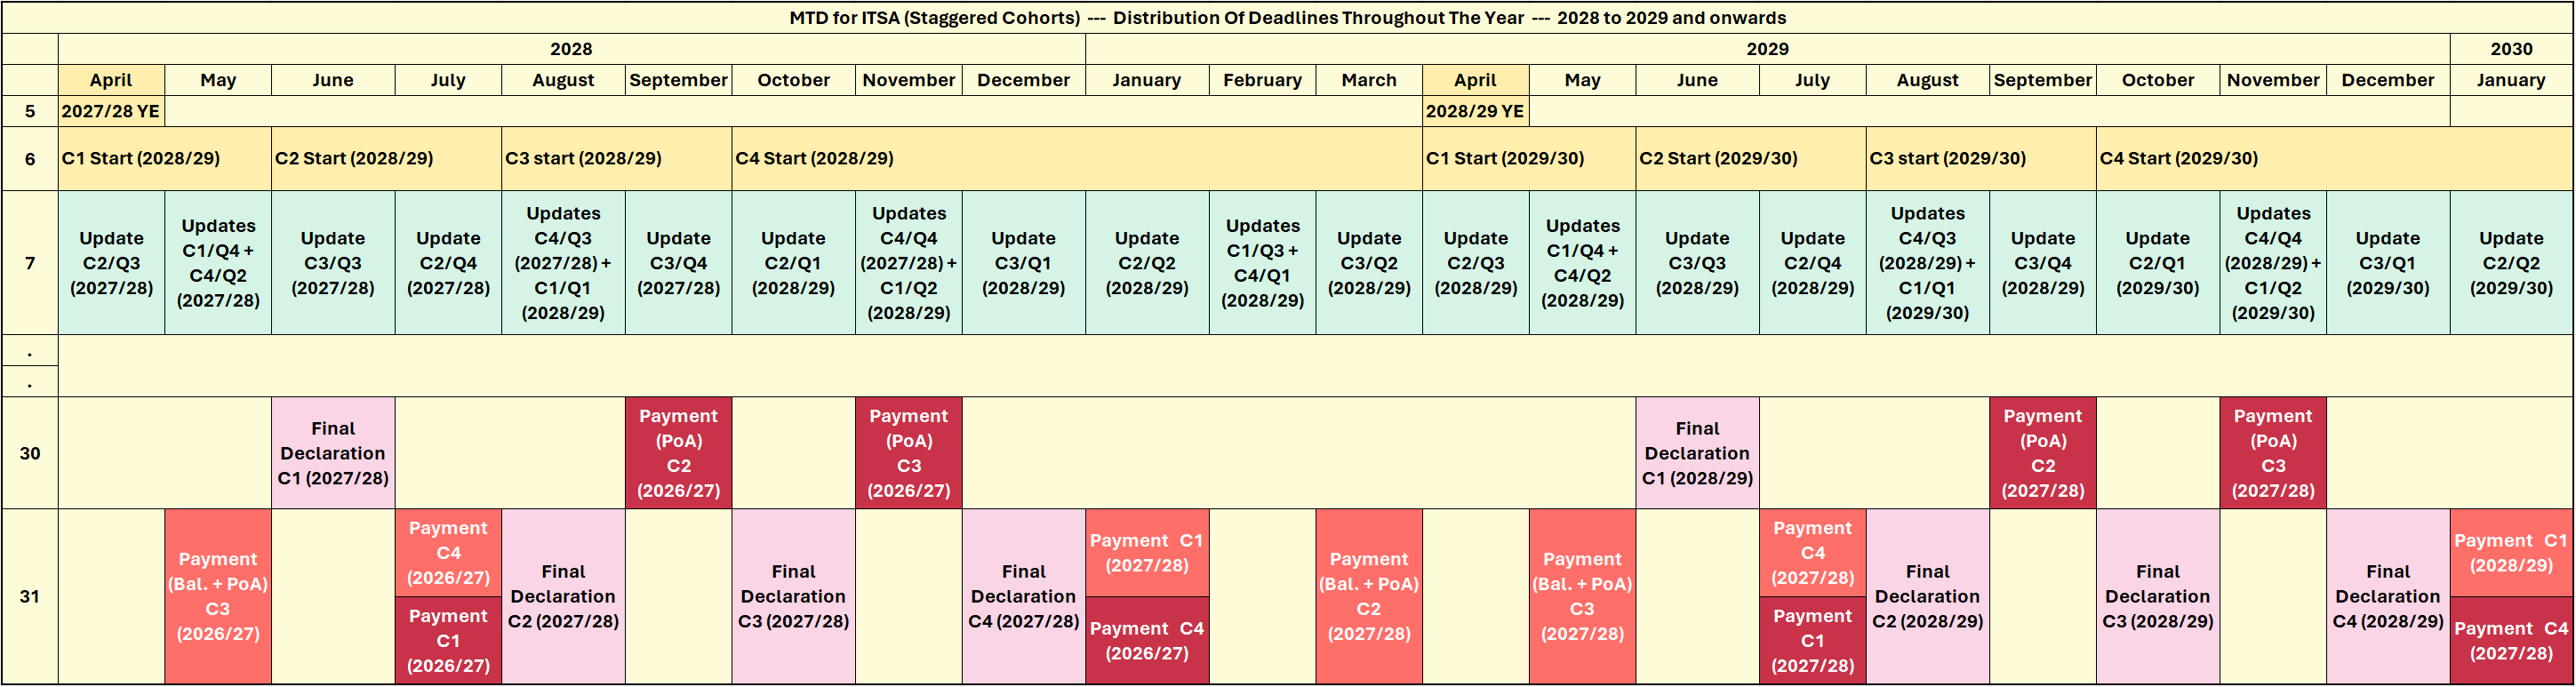
The normalised schedule of events and deadlines in the second year, beginning on 6 April 2028 is presented in figure 3. Figure 3.1 presents the fully normalised, repeating staggered cohorts calendar covering the tax year 2028/29.
Each newly joined taxpayer's schedule is normalised at the beginning of their second annual reporting period, on submitting their final declaration before their first quarterly update deadline for the new period.
The new schedule of reporting and payments deadlines distributes the most demanding activity more evenly across the calendar year. Individual taxpayers still meet the demands of only seven fixed deadlines but the scale of peak demands, on services and agents, is reduced because each new deadline serves only a fraction of the MTD population, and taxpayers final declaration deadlines no longer converge with their payment deadlines.
Click on the image to view a larger format.
Newly mandated registrants under this scheme enter the MTD regime on one of 4 cohort start dates, on the 6 April, 6 June, 6 August or 6 October, and report on an annual cycle determined by their initial start date. Their start date becomes the first day of a new registrant's tax reporting year.
Existing users continue the 6 April to 5 April basis — already aligned with the statutory tax year.
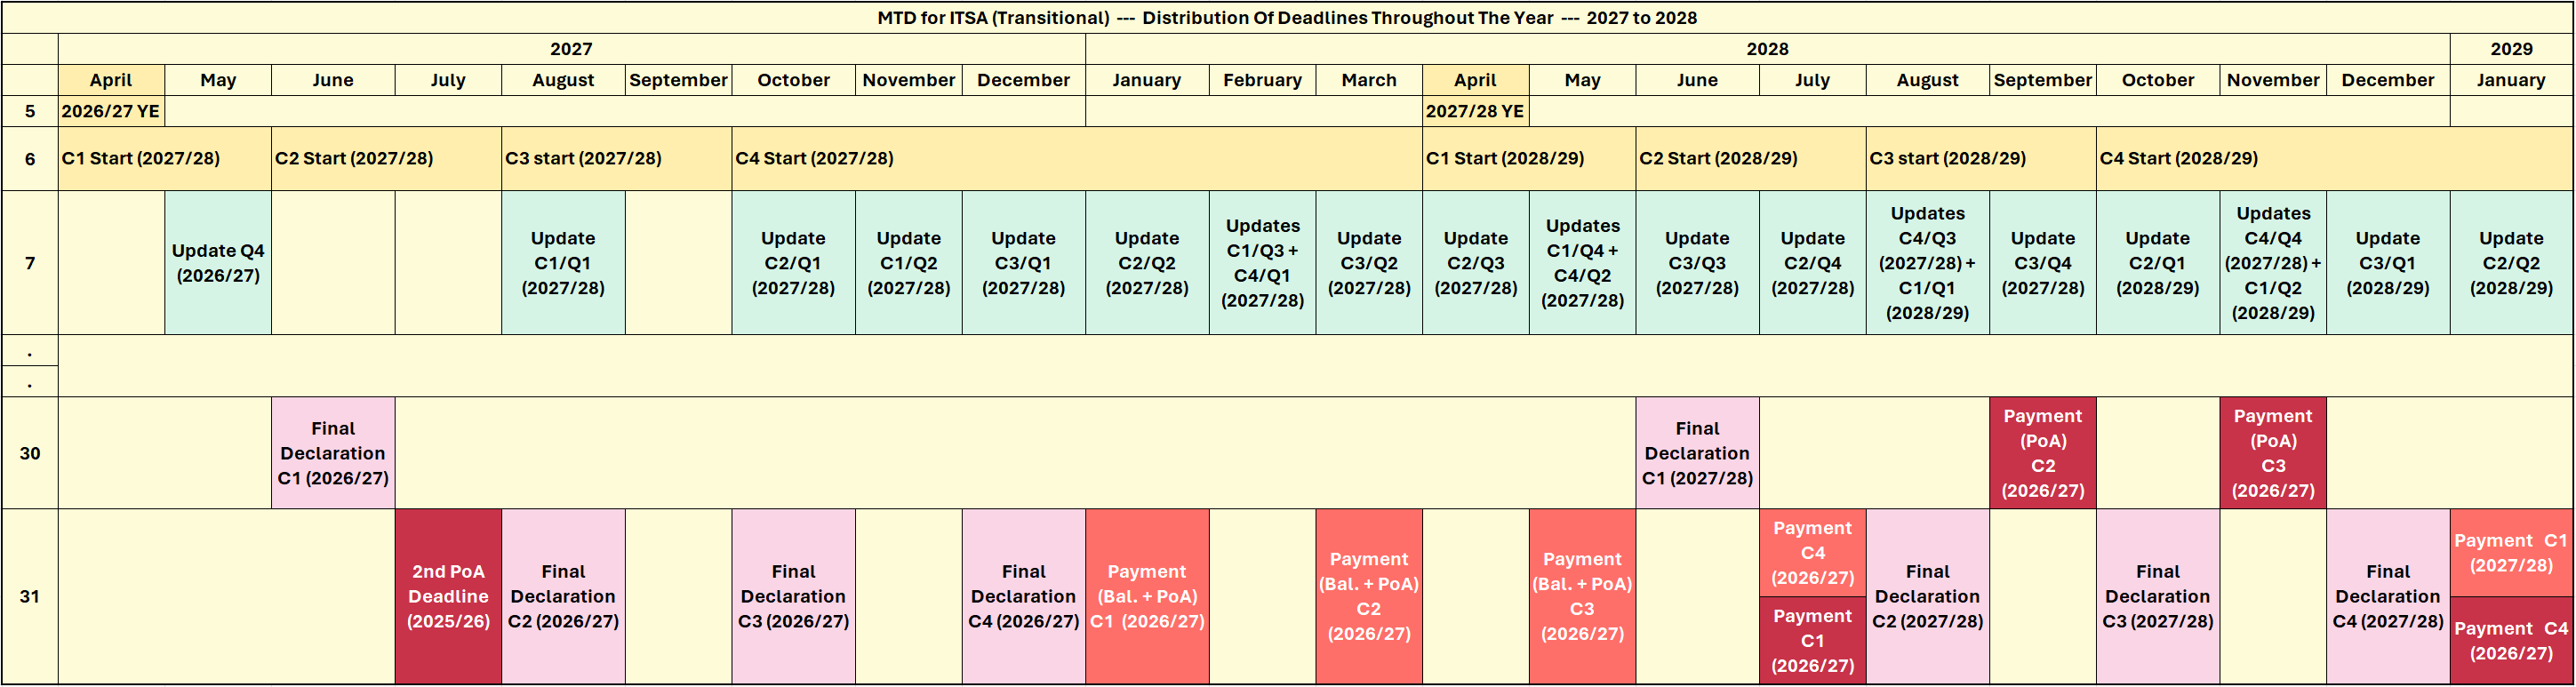
Taxpayers who join during the 2027/28 statutory tax period enter cohort C2, C3 or C4, introducing a pause on new entrants joining C1, which already serves the large population of taxpayers in scope from 2026/27.
Click on the image to view a larger format.
Click on the image to view a larger format.
Click on the image to view a larger format.
All 4 cohorts experience a permanent change in the timing of deadlines, bringing final declaration deadlines forward, within 90 days of any cohort's tax reporting year end. The change is most dramatic in the first year of operation:
- Existing taxpayers in cohort C1 would submit their final declaration by 30 June 2027, seven months earlier than the current statutory 31 January 2028.
- Taxpayers joining cohort C2 would submit their final declaration by 31 August 2027, five months earlier than the current statutory 31 January 2028.
- Taxpayers joining cohort C3 would submit their final declaration by 31 October 2027, three months earlier than the current statutory 31 January 2028.
- Taxpayers joining cohort C4 would submit their final declaration by 31 December 2027, one month earlier than the current statutory 31 January 2028.
Following implementation, each cohort's balance and first payment on account deadline falls seven months after their final declaration deadline rather than falling on the same day.
The Merits
- Symmetry of information (the primary objective). Each cohort's final declaration date falls less than 90 days after the previous tax year's end, before their Q1 update deadline, closing the 9-month information gap, enabling the taxpayer to proceed with known figures in place of estimates. The declaration deadline stands alone, decoupled from any other deadline — making "file early" campaigns redundant, because early finalisation is no longer voluntary behaviour the taxpayer must be persuaded into, but a mandatory deadline.
- Congestion relief (a second-order consequence). The design successfully staggers final declaration deadlines across the year: C1 finalises in June, C2 in August, C3 in October and C4 in December. These are the agent-intensive events, decoupled from any payment obligation. Payments remain more concentrated than declarations: each cohort retains two settlement dates spaced six months apart, which concentrates eight payment events into six months (January, March, May, July, September, November). Crucially, January and July carry two cohorts' payment obligations each, because C1's balancing and first payment on account (January) coincides with C4's second payment, and vice versa in July. This double‑booking leaves the system exposed to settlement pressure in those two months, but declaration traffic — which drives the agent workload and helpline strain — is genuinely distributed. The design therefore trades the current universal January peak for a flatter calendar of declaration deadlines, accepting that payments will still cluster more narrowly. Similarly, May, August, November and February each carry two cohorts' quarterly update deadlines, resulting in increased reporting activity in these months.
- System resilience. HMRC infrastructure and support lines face demand waves rather than a single surge for declarations and agent-facing work. Settlement pressure remains concentrated in January and July (two cohorts' payments each), but declaration traffic — which drove the 2026 helpline strain and Agent Dedicated Line closure (ICAS, 2026a; ICAEW, 2026) — is now spread across the year.
Objections
Transparency requires acknowledging the difficulties.
- Statutory interlock. Rates, allowances, National Insurance and benefits are all computed on the statutory April to April tax year basis. Any scheme under which a taxpayer's income is allocated by reference to a different reporting period would require reconciliation between reporting period and tax period — a complexity basis period reform spent years dismantling (Tax Adviser magazine, 2023; ATT, 2024). Scepticism is fair — basis period reform was undertaken because successive regimes judged misaligned reporting unacceptable. Staggered cohorts propose a constrained approach, designed to make reconciliation an exception rather than a norm, and to minimise any consequences should reconciliation be required.
This discussion invites professional appraisal and challenges the government to question whether permitting a constrained overlap between reporting and tax year periods could avoid increasing strain on the systems, and the profession, as the mandated population grows.
A brief examination of situations that would require reconciliation between reporting and tax periods follows.
Again, the change is most dramatic in the first year of operation.
In the first year of staggering cohorts, beginning on 6th April 2027 assuming no change in income tax allowance during the whole period in question, the different cohorts' experience changes in deadlines. Cohorts C2, C3 and C4's 2026/27 liability (old deadline 31 January 2028) is deferred to the new 31 March / 31 May / 31 July 2028 payment dates, falling fourteen, sixteen and eighteen months after their last declaration (submitted before 31 January 2027 for the year ending 5 April 2026).
- C1, who report on the period 6 April 2027 to 5 April 2028, submit their final declarations for the previous year by 30th June 2027 and retain the 31 January 2028 balancing and first payment deadline.
- C2, who begin reporting on the period 6 June 2027 to 5 June 2028, submit their final declarations for the previous year (6 April 2026 to 5 June 2027) by 31 August 2027 and have a new balancing and first payment deadline on 31 March 2028 (the new deadline going forward), fourteen months after their previous 31 January 2027 deadline. The cohort declares income for a fourteen month period. The main consideration is controlling cash flow, anticipating a balancing payment added to the next payment on account.
- C3, who begin reporting on the period 6 August 2027 to 5 August 2028, submit their final declarations for the previous year (6 April 2026 to 5 August 2027) by 31 October 2027 and have a new balancing and first payment deadline on 31 May 2028 (the new deadline going forward), sixteen months after their previous 31 January 2027 deadline. The cohort declares income for a sixteen month period, extending the duration of the associated cash flow planning period even further.
- C4, who begin reporting on the period 6 October 2027 to 5 October 2028, submit their final declarations for the previous year (6 April 2026 to 5 October 2027) by 31 December 2027 and have a new balancing and first payment deadline on 31 July 2028 (the new deadline going forward), eighteen months after the previous 31 January 2027 deadline. The cohort declares income for an eighteen month period, once again extending the duration of the associated cash flow planning period.
In subsequent years, each cohort follows a regular 12-month annual reporting and payments cycle. Reconciliation between reporting and tax periods is triggered by legislative change, not by the date shift itself: only where allowance rates or thresholds change does apportionment become necessary following that change. In all other years, the reporting-year computation and the statutory computation produce the same liability.
Consider such a change occurring on 6 April 2028, after implementing a staggered cohort framework.
- C1 remains unaffected, given that its reporting year coincides with the statutory tax year.
- C2, whose first staggered reporting year began on 6 June 2027, needs to make a final declaration adjustment associated with the profit earned during the 2027/28 tax year: Net income for the whole year must be apportioned, calculating tax due from the share of income for the period 6 June 2027 to 5 April 2028 using the old thresholds and rates, and applying the new thresholds and rates to calculation of tax on the share of income for the period 6 April 2028 to 5 June 2028.
- C3 would require similar treatment, calculating tax due from the share of income for the period 6 August 2027 to 5 April 2028 using the old thresholds and rates, and applying the new thresholds and rates to calculation of tax on the share of income for the period 6 April 2028 to 5 August 2028.
- C4 follows the same rule.
These adjustments add complexity but the statutory April to April tax period basis survives.
It is worth situating this objection against current policy direction. HMRC's consultation on timely payment of income tax (published 23 June 2026) proposes collecting forecast ITSA liabilities through PAYE from April 2029 for taxpayers with PAYE income, and more frequent in-year payments for others; ICAS's response supported the broad objective while raising concerns about cash-flow shocks, administrative burden, and the reliability of in-year forecasting (ICAS, 2026b). Payment-date reform is therefore already on the table and proposes moving everyone to more frequent payments.
Staggered cohorts distribute settlement traffic across six months of the year rather than two, providing more frequent cash inflows to HMRC by design. This could give weight to an argument against government proposals to increase the frequency of payments for taxpayers outside the PAYE regime.
- Agent-level reconcentration. A substantial share of quarterly updates and final declarations flow through agents, and staggering taxpayer deadlines does not automatically stagger agent workload: if an agent's client books were to consolidate within a single cohort, peak-season concentration would reappear for that agent. A UTR-banded assignment rule could mitigate this risk. Client books would mix across cohorts naturally, because a typical practitioner's clients span the banding at random — the diversification is then a statistical product of the assignment, not something each agent must engineer. It should be noted however, that staggered cohorts with staggered deadlines and a UTR-banded assignment rule, only statistically staggers workload, but doesn't guarantee a staggered workload.
- Disproportionate cohort population size. C1 submits its 2026/27 declaration by 30 June 2027, seven months earlier than the statutory 31 January 2028. If all 864,000+ existing users plus April-starters share one calendar, the "staggering" concentrates the largest population segment into a single June declaration and a single 31 January payment deadline. The document's congestion-relief claim rests on distributing deadlines, yet C1 would be far larger than C2 to C4 combined in the early years. Mandating new registrants into joining C2, C3 and C4 during the early years could offer a form of mitigation, and combined with churn2, gradually reducing C1's population, the most adverse outcome could be averted. UTR-banded assignment could provide a further useful control.
- Coinciding payment deadlines. C1's balancing and first payment date (31 January) coincides with C4's second payment date, and vice versa in July: C4's balancing and first payment falls on 31 July, alongside C1's second payment. January and July therefore each carry two cohorts' settlement obligations. However, these coincident events are payment-only — neither is coupled to a final declaration deadline (C1 declares in June, C4 in December) — so they represent settlement traffic rather than the agent-intensive declaration workload that drives congestion under the current design.
- Coinciding reporting deadlines. Acknowledged in The Merits section, May, August, November and February each carry two cohorts' quarterly update deadlines, resulting in increased reporting activity in these months. These deadlines affect only quarterly updates, which are considerably less demanding in preparation compared with final declarations.
Operational Feasibility: An Invitation to the Profession
This section is an invitation to practising agents and accountants to stress-test the proposal against the operational realities of their workflows. The author is a software developer, not a practising accountant. The design logic is the author’s; the verdict on operability belongs to the profession.
Four dimensions of the staggered cohort model require empirical validation before any formal adoption could be considered. Practitioners are uniquely placed to assess the first three against the constraints of daily practice; the fourth — the readiness of software and systems — raises questions for HMRC’s API developers and third-party software vendors.
Transitional Long-Period Declarations
Cohorts C2, C3 and C4 submit declarations for fourteen, sixteen and eighteen-month periods respectively in the first year. For sole traders and landlords, this means:
- Capital allowances must be calculated on non-standard periods. Software packages need to handle apportionment rules correctly without double-counting or omitting items that fall across two statutory tax years.
- Loss relief claims may need to be split or repositioned. If a loss arises in an eighteen-month period, how is it carried forward into subsequent twelve-month cycles?
- Client records maintained on a calendar-year or commercial-year basis will need conversion to the cohort reporting year. Is this administratively feasible at scale, or does it impose disproportionate burdens on smaller businesses without dedicated accounting support?
Additional questions for practitioners: Would your typical client portfolio be able to comply with these transitional periods without significant additional workload or error risk? Which client segments would struggle most?
Agent Workload Distribution
The proposal assumes that UTR-banded assignment and statistical mixing could help to smooth agent workloads. This deserves scrutiny.
- Client consolidation. As the objections above acknowledge, UTR-banded assignment only statistically staggers workload — the open question is whether that suffices in practice: if an agent’s client base happens to cluster in one UTR band, they may inherit a full cohort rather than a spread. Does the UTR-banded approach mitigate this risk sufficiently?
- Staffing and resourcing. Practices have invested in staffing models for the current January peak. A staggered calendar changes those models fundamentally. Are practices equipped to manage declaration traffic in June, August, October and December without hiring additional staff?
- Software integration. MTD-compatible software must handle multiple cohort schedules simultaneously. Do current platforms support this, or would new development be required?
Additional questions for practitioners: Would your firm’s resourcing model accommodate staggered deadlines, or would you need to hire to cover peaks outside January? How confident are you that UTR-banding would distribute your client books evenly?
Cash Flow Implications for Clients
The longer declaration periods in the transition phase defer payments on account for C2, C3 and C4 by fourteen, sixteen and eighteen months. While this may help cash flow for some, it creates uncertainty for others.
- Forecasting. Businesses rely on predictable payment dates to plan provision. Irregular intervals (fourteen, sixteen or eighteen months, then seven months thereafter) between each cohort’s final declaration deadline and first payment on account complicate budgeting through the transitional period.
- Interest and penalties. HMRC guidance will need to clarify whether interest runs differently for irregular payment intervals. Is there a risk of unintended penalties if taxpayers misunderstand the new schedule?
- PAYE vs. Self-Assessment. Where clients have PAYE income alongside property or trading income, aligning the two streams under a staggered regime may introduce reconciliation complexities.
Additional questions for practitioners: Would your clients prefer shorter, more frequent payment windows (as proposed by HMRC’s timely payments consultation) or fewer but more predictable ones? Where do you see the greatest cash-flow friction in practice?
Data Integrity and Software Readiness
Software vendors could face significant development work to support cohort logic, and the current MTD API design assumes a uniform reporting calendar; altering this may require deeper architectural changes.
- API compatibility. Will the MTD API support cohort-specific reporting periods, or is it hardcoded to the 6 April to 5 April cycle?
- Version control. During the transition, HMRC systems must simultaneously process legacy (cohort C1) and new (C2–C4) submissions. Is the infrastructure ready for mixed-mode operations?
- Error handling. When software calculates apportionments across reporting and statutory years, where do errors occur? Are there safeguards to prevent incorrect tax computations due to software misinterpretation?
Additional questions for software providers: Is your platform prepared to handle staggered cohort schedules without custom development? What technical constraints would limit deployment?
Conclusion
MTD was justified as a modernisation, promising to deliver real-time visibility and reduced error, yet its endpoint preserves the defining disorder of the old system: a universal information gap capped by a single national deadline. On the currently implemented MTD calendar, the financial figures a late-filing taxpayer relies upon are nothing more than estimates, for up to nine months after their year-end, with their confirmed income tax position potentially arriving on the same date as the payment it triggers. The quarterly architecture distributes routine reporting admirably — with deadlines falling on 7 August, 7 November, 7 February and 7 May — only to reconcentrate everything consequential in January. Professional opinion has converged on the diagnosis from several directions: ICAEW on the pace of extension, ICAS on both the unsuitability of quarterly updates for liability estimation and the visible strain on HMRC's support channels at the January peak (ICAS, 2026a; ICAS, 2026b).
The discussion here has argued that this concentration is not curable by appeals to taxpayer behaviour, because the option to file early has always existed and offers the taxpayer nothing in return for taking it. The January peak is caused by the aggregate of individually rational delay, anchored by compulsory payment dates. Remedies that leave those anchors in place — encouragement, awareness campaigns, voluntary schemes — cannot succeed, and should not be presented as if they could.
This discussion has argued that the measure of a corrected design is primarily informational: confirmed figures within 90 days of each cohort's reporting year end, and a finalisation deadline that no longer coincides with the payment it triggers. The distribution of declaration and settlement traffic across the year is a second-order consequence of the same change — a welcome one, on the evidence of HMRC's own January support arrangements, supporting the primary objective.
One question lies beyond this design's reach: a mandated population of roughly a quarter of Self-Assessment is small enough that the case for the disruption must be made rather than presumed. This paper does not make that case but offers the more modest assurance that if the mandated population is to bear these costs, the calendar it is asked to operate should at least deliver the benefit the reform was named for.
What remains are structural measures: the staggered cohort proposal set out above, and rolling commencement under which a taxpayer's obligations begin at the first appropriate quarterly boundary after they fall within scope rather than a fixed 6 April. Neither measure is unprecedented: VAT already assigns its registered population to stagger groups, so that return and payment deadlines fall in different months for different businesses, staggered by HMRC expressly “to spread the flow of returns evenly over the year” (HMRC, n.d.) — an ordinary, largely uncontroversial feature of the system. The two are complementary rather than alternatives: the tranches of 2027 and 2028 are large enough that their arrival should not be synchronised, and rolling commencement is the natural vehicle by which each tranche enters.
Both merit formal evaluation, and the natural moment is before the final tranche arrives — the January 2028 peak, when the first mandatory cohort submits its final declarations, will supply the clearest evidence yet of what synchronisation costs (ICAEW, 2025). The operational feasibility questions set out above are offered as the starting point for that appraisal.
The congestion is real, predictable and measurable — the 5.65 million unresolved filings at 5 January 2026 quantify today's baseline (HMRC, 2026d), and the January 2028 peak will supply the sharper evidence. Whether the government's preference for statutory simplicity justifies it is precisely the question that evidence should inform — alongside the parallel question of what the disruption, confined to a quarter of the filing population, is ultimately for.
Note 1. In fact, taxpayers whose accounting period runs 1 April–31 March can elect calendar update periods (joining from 1 April rather than 6 April), per GOV.UK guidance. (HMRC, 2026b).
Note 2. HMRC does not routinely publish figures on how many people enter or leave Self-Assessment each year.
References
- Association of Taxation Technicians (ATT) (2024). Basis Period Reform — FAQs. Available at: att.org.uk — Basis period reform [Accessed 02 November 2026].
- Association of Taxation Technicians (ATT) (2026). MTD sign up issues: practical guidance for agents. Available at: att.org.uk — Practical guidance for agents [Accessed 02 November 2026].
- HM Government (2025). Making Tax Digital for Income Tax Self-Assessment for sole traders and landlords. Policy paper. Available at: gov.uk — MTD ITSA for sole traders and landlords [Accessed 02 November 2026].
- HM Government (2026a). Sole traders and landlords earning more than £30,000 urged to act now. Press release. Available at: gov.uk — Sole traders and landlords urged to act now [Accessed 02 November 2026].
- HM Government (2026b). Reduction of the mandation threshold from £30,000 to £20,000 from April 2028. Policy paper. Available at: gov.uk — Reduction of the mandation threshold [Accessed 02 November 2026].
- HMRC (n.d.). Debt Management and Banking Manual, DMBM530020: VAT — Introduction to VAT — General. Available at: gov.uk — DMBM530020 [Accessed 02 November 2026].
- HMRC (2025). Ready, Steady, File! Correspondence. Available at: gov.uk — Ready, Steady, File! [Accessed 02 November 2026].
- HMRC (2026a). Deadline approaches for first Making Tax Digital quarterly update. Press release, 23 July. Available at: gov.uk news [Accessed 02 November 2026].
- HMRC (2026b). Use Making Tax Digital for Income Tax: Send quarterly updates. Available at: gov.uk — Send quarterly updates [Accessed 02 November 2026].
- HMRC (2026c). 436,000 sole traders and landlords make their tax digital. Press release, 12 August. Available at: gov.uk news [Accessed 02 November 2026].
- HMRC (2026d). 5.65 million still to file as the Self-Assessment deadline looms. Press release, 5 January. Available at: gov.uk news [Accessed 02 November 2026].
- ICAEW (2025). MTD income tax will be extended in 2028. ICAEW Insights, March. Available at: icaew.com [Accessed 02 November 2026].
- ICAEW (2026). HMRC support for taxpayers and agents on 31 January. ICAEW Insights, January. Available at: icaew.com [Accessed 02 November 2026].
- ICAS (2023a). ICAS calls for new approach to making tax digital for income tax self-assessment (MTD for ITSA) quarterly reporting, 29 June. Available at: icas.com [Accessed 02 November 2026].
- ICAS (2023b). Making Tax Digital and follow up to meeting on 7 June 2023. Letter, 29 June. Available at: Letter to Kevin Hollinrake (PDF) [Accessed 02 November 2026].
- ICAS (2026a). Update on HMRC support for self-assessment deadline, 29 January. Available at: icas.com [Accessed 02 November 2026].
- ICAS (2026b). Grant, G. ICAS responds to the HMRC Timely Payments in Income Tax Self-Assessment (ITSA) consultation, 25 August. Available at: icas.com [Accessed 02 November 2026].
- Tax Adviser magazine (2023). Basis period reform: transitional rules apply from 6 April 2023. Available at: taxadvisermagazine.com [Accessed 02 November 2026].